Compare SIP vs FD on returns, tax efficiency, and liquidity. SIP beats FD for long-term wealth creation and inflation protection. Use our live SIP vs FD calculator and start investing today.
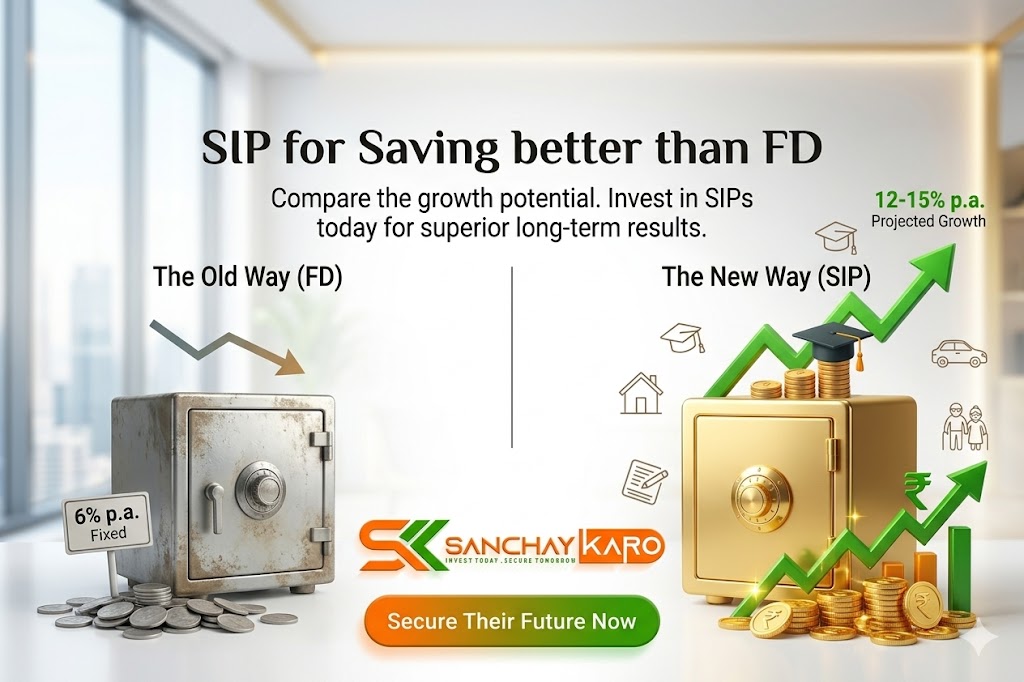
SIP offers inflation-beating returns, tax efficiency, and flexibility that no FD can match.
SIP in equity mutual funds historically delivers 12–15% returns vs FD's 6–7.5%. Over 15 years, ₹5,000/month in SIP can grow to ₹25 lakh+ vs FD's ₹14 lakh.
FD returns at 7% minus 6% inflation = just 1% real return. SIP at 12–15% beats inflation comfortably, preserving your purchasing power for retirement or child education.
FD interest taxed up to 39% as per slab. Equity SIP LTCG: only 12.5% above ₹1.25L gains. ELSS SIP saves ₹1.5L under Section 80C too.
SIP has no lock-in (except ELSS 3 years). Redeem anytime at no penalty. FD premature withdrawal costs 0.5–1% lower interest rate.
Enter your monthly amount and instantly see how much more SIP earns versus FD.
Compare wealth at maturity – same investment, same period, different instruments
A detailed side-by-side breakdown to help you decide for your goals.
| Parameter | ✅ SIP (Equity Mutual Funds) | 🏦 Fixed Deposit (FD) |
|---|---|---|
| Expected Returns (p.a.) | 12–15% (historical equity) | 6–7.5% (bank/NBFC) |
| Inflation-Adjusted Returns | Positive – beats inflation | Often negative after tax & inflation |
| Lock-in Period | No lock-in (ELSS: 3 years only) | 1–10 years with premature penalty |
| Premature Withdrawal Penalty | No penalty (exit load ≤ 1% for <1 yr) | 0.5–1% lower interest + bank penalty |
| Tax on Returns | LTCG: 12.5% above ₹1.25L gains STCG: 20% if held < 1 year | Added to income; taxed at slab rate (up to 39%) |
| Tax Saving Under 80C | ELSS SIP: up to ₹1.5L deduction | Only 5-year tax-saver FD (same ₹1.5L cap) |
| TDS Deduction | No TDS on mutual fund redemptions | TDS @10% if interest > ₹40,000 (₹50,000 for seniors) |
| Risk Level | Moderate–High (reduces over 10+ yrs) | Very Low (principal protected) |
| Minimum to Start | ₹500/month SIP | ₹1,000+ lump sum |
| Best For | Goals 5+ years: retirement, child education, wealth creation | Short-term 1–3 years; emergency fund; capital preservation |
Verdict: For goals beyond 5 years, SIP consistently outperforms FD due to higher inflation-adjusted returns and superior tax efficiency. For short-term needs (1–3 years) or capital preservation, FD remains a safe choice. Consider hybrid SIP funds (debt + equity) if you want moderate risk with better-than-FD returns.
Switch from FD to SIP and enjoy higher long-term growth, tax savings, and flexibility.
Install from Google Play or App Store — free, fast, and fully digital.
Aadhaar + PAN based verification in minutes — no branch visit needed.
Retirement, child education, or wealth creation — pick what matters most to you.
Select from large cap, mid cap, or hybrid funds with 12%+ historical returns.
Begin at just ₹500/month. Increase step-up yearly as your income grows.
Fill the form below. Our team will assist you with paperless KYC and guide you to SIP funds that beat FD.
Thousands have switched from FD to SIP and built far greater long-term wealth.
One app — compare SIP vs FD, use our calculator, and start building real wealth today.
Disclaimer: This page is for educational and illustrative purposes only. Historical returns do not guarantee future performance. Mutual fund investments are subject to market risks. Please read all scheme-related documents carefully. Pallab Routh (ARN-301757) is an AMFI-registered Mutual Fund Distributor.
 Google Play
 App Store